PET 2026 · Economy
GST and the taxes it replaced वस्तु एवं सेवा कर (GST) और कर सुधार Compare post-1991 tax reform committees, taxes subsumed into GST, excluded taxes and dual GST 1991 के बाद की कर सुधार समितियाँ, GST में समाहित कर, बाहर रखे गए कर और दोहरा GST ढाँचा
◈
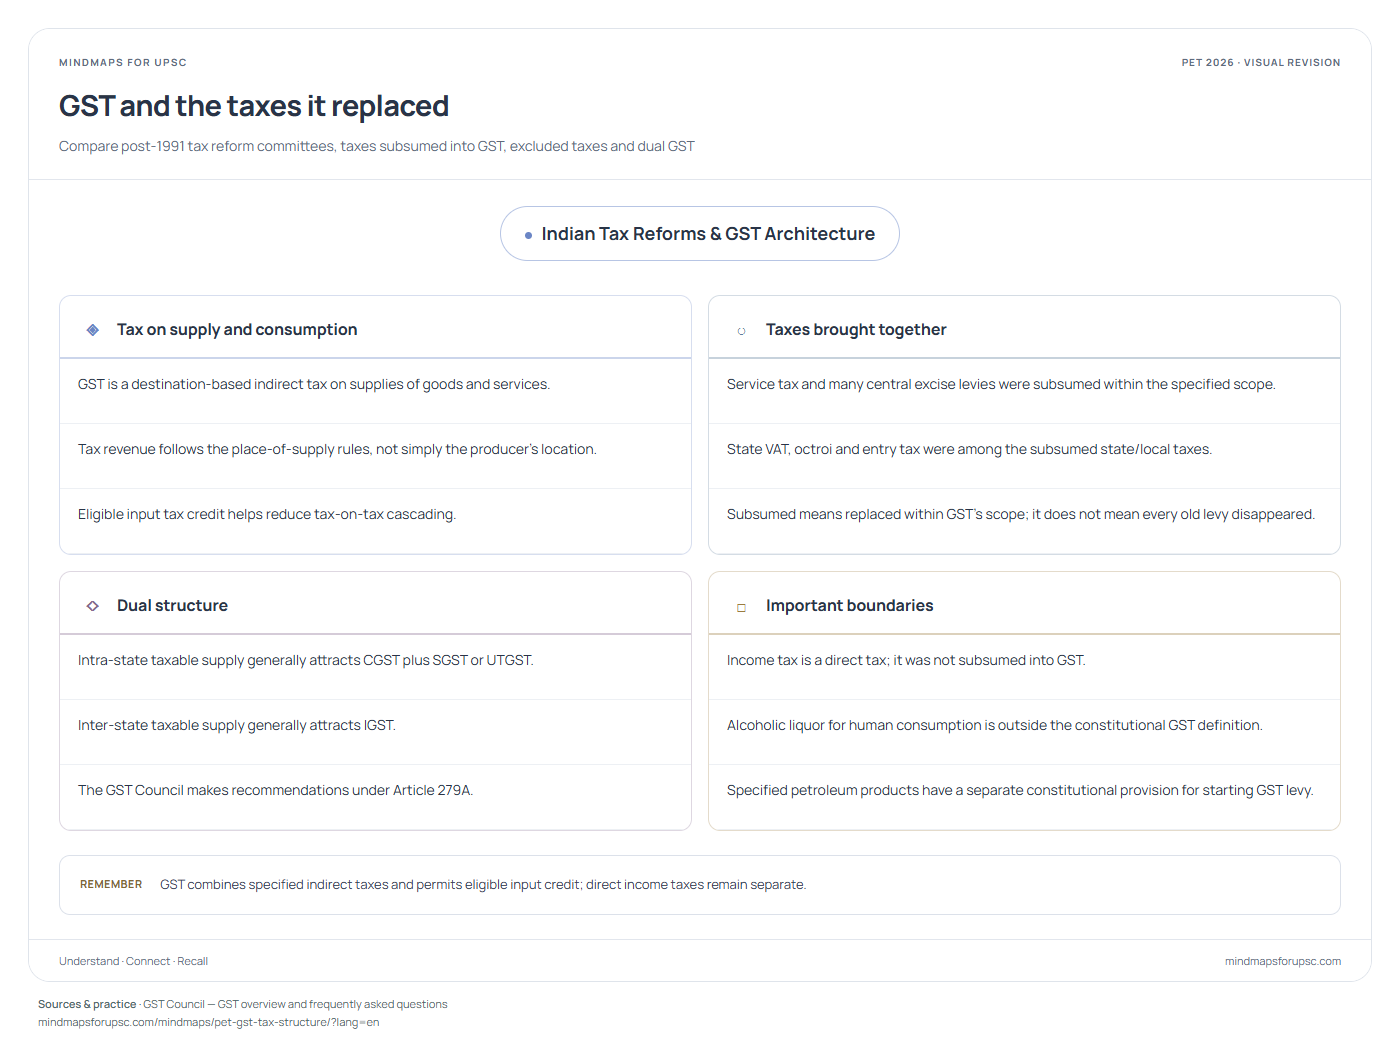
Tax on supply and consumption
GST is a destination-based indirect tax on supplies of goods and services. Tax revenue follows the place-of-supply rules, not simply the producer’s location. Eligible input tax credit helps reduce tax-on-tax cascading.
○
Taxes brought together
Service tax and many central excise levies were subsumed within the specified scope. State VAT, octroi and entry tax were among the subsumed state/local taxes. Subsumed means replaced within GST’s scope; it does not mean every old levy disappeared.
◇
Dual structure
Intra-state taxable supply generally attracts CGST plus SGST or UTGST. Inter-state taxable supply generally attracts IGST. The GST Council makes recommendations under Article 279A.
□
Important boundaries
Income tax is a direct tax; it was not subsumed into GST. Alcoholic liquor for human consumption is outside the constitutional GST definition. Specified petroleum products have a separate constitutional provision for starting GST levy. Remember GST combines specified indirect taxes and permits eligible input credit; direct income taxes remain separate.
◈
आपूर्ति और उपभोग पर कर
GST वस्तुओं और सेवाओं की आपूर्ति पर गंतव्य-आधारित अप्रत्यक्ष कर है। कर-राजस्व का निर्धारण आपूर्ति-स्थान के नियमों से होता है, केवल उत्पादक के स्थान से नहीं। पात्र इनपुट टैक्स क्रेडिट कर पर कर लगने के प्रभाव को घटाता है।
○
समाहित किए गए कर
निर्दिष्ट दायरे में सेवा कर और कई केंद्रीय उत्पाद शुल्क GST में समाहित हुए। राज्य वैट, चुंगी और प्रवेश कर समाहित राज्य/स्थानीय करों में शामिल थे। समाहित होने का अर्थ GST के दायरे में प्रतिस्थापन है; हर पुराने कर का समाप्त होना नहीं।
◇
दोहरा ढाँचा
राज्य के भीतर करयोग्य आपूर्ति पर सामान्यतः CGST के साथ SGST या UTGST लगता है। अंतर-राज्यीय करयोग्य आपूर्ति पर सामान्यतः IGST लगता है। GST परिषद अनुच्छेद 279क के अंतर्गत सिफारिशें करती है।
□
महत्त्वपूर्ण सीमाएँ
आयकर प्रत्यक्ष कर है; इसे GST में समाहित नहीं किया गया। मानव उपभोग की मदिरा GST की संवैधानिक परिभाषा से बाहर है। निर्दिष्ट पेट्रोलियम उत्पादों पर GST आरंभ करने का अलग संवैधानिक प्रावधान है। याद रखें GST निर्दिष्ट अप्रत्यक्ष करों को जोड़ता है और पात्र इनपुट क्रेडिट देता है; प्रत्यक्ष आयकर अलग रहता है।
Practise this concept · संबंधित प्रश्न One visual, several questions. These links open the original paper at the matching question.
Sources & study notes · स्रोत Independent revision material, linked to the paper’s concepts. The question papers and answer-key status are available on OpenPYQ.